


Notice
You are now leaving the Third Avenue Management website and being connected to a third-party website. Please note that Third Avenue Management is not responsible for the information, content or products(s) found on third-party websites.
Notice
Third Avenue Management is aware of recent incidents involving unauthorized individuals and groups falsely claiming to represent Third Avenue Management and its affiliates through social media platforms, messaging applications, email, and fraudulent websites. In some cases, these bad actors have used the names, photographs, or identities of Third Avenue employees in an attempt to appear legitimate.
These individuals and websites are not affiliated with, sponsored by, or endorsed by Third Avenue Management.
Third Avenue Management does not solicit investments, provide investment recommendations, or request personal or financial information through social media platforms or messaging applications such as WhatsApp, Telegram, Signal, or similar services.If you receive a suspicious communication claiming to be from Third Avenue Management, we encourage you to verify its authenticity before responding or providing any personal or financial information. If you are unsure whether you are communicating with an authorized representative of Third Avenue, please contact us directly using the contact information available on our official website.
Third Avenue Management, its affiliates, directors, officers, employees, and agents are not responsible for communications, representations, or activities conducted by unauthorized third parties. If you believe you have been the target of an impersonation or investment scam, or that you or someone you know has been a victim of fraud, please contact your local law enforcement agency and report the incident to the appropriate authorities. In the United States, suspected internet fraud can also be reported to the Federal Bureau of Investigation's Internet Crime Complaint Center (IC3) at https://www.ic3.gov/.
Notice
You are now leaving the Third Avenue Management website and being connected to a third-party website. Please note that Third Avenue Management is not responsible for the information, content or products(s) found on third-party websites.
September 30, 2026
International Real Estate Value Fund
International Real Estate Value Fund Q326


Dear Fellow Shareholders,
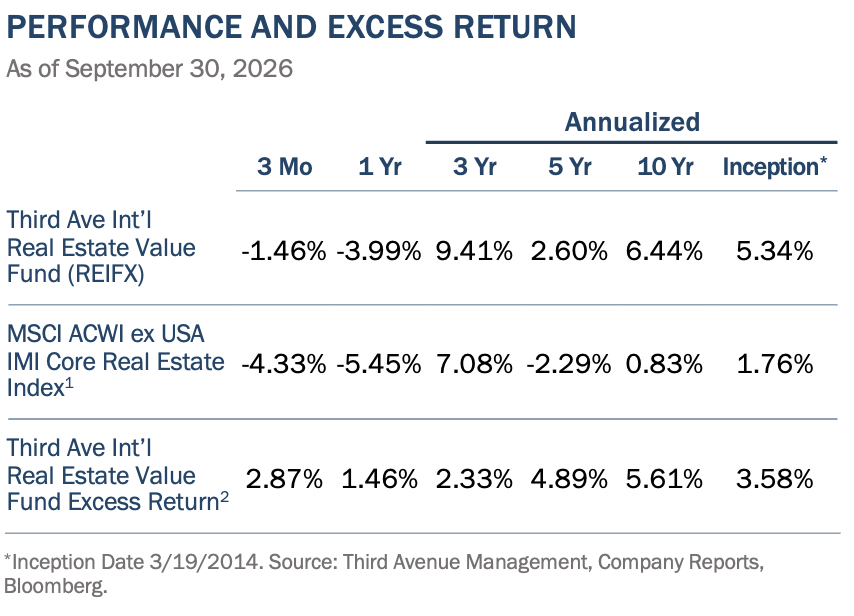
We are pleased to provide you with the Third Avenue International Real Estate Value Fund (the “Fund”) report for the quarter ended September 30, 2026. The Fund delivered a return of -1.46% (after fees) for the quarter, outperforming the MSCI ACWI ex USA IMI Core Real Estate Index1 (the “Index”), which returned -4.33% over the same period. Year-to-date, the Fund has returned -2.87%, compared with -6.24% for the Index. Over the last 10 years, the Fund has outperformed the Index by 5.61% per year (after fees).
The modest declines in international listed real estate share prices during the quarter were largely due to higher interest rates and ongoing energy flow disruptions in the Middle East and Russia/Ukraine. This extends a period in which valuations have moved sideways, or lower, even as the underlying earnings of the Fund’s holdings have continued to compound higher. Fund Management used this weakness to concentrate capital in its highest-conviction opportunities, adding to four existing positions where discounted valuations and identifiable catalysts are most compelling, while trimming several holdings that have generated strong returns. In addition, private capital continued to recognize the value disconnect, as Fund holding Ingenia Communities Group received multiple all-cash privatization proposals from affiliates of private equity firm Warburg Pincus.
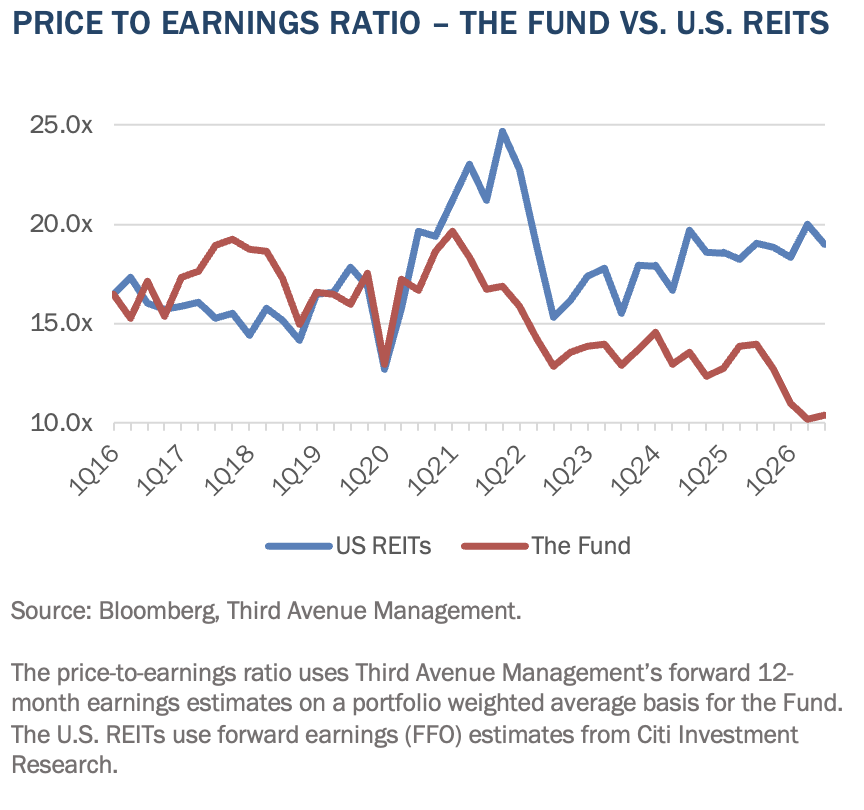
Against this backdrop, International real estate remains a compelling opportunity in our view, with the Fund’s very well capitalized holdings trading at 10 times earnings on a weighted-average basis, roughly half the valuation multiple of U.S. REITs, despite seemingly better earnings growth. Fund Management believes this valuation gap is unprecedented and unsustainable, with the Fund positioned to benefit as it closes. With equity markets increasingly concentrated in a narrow AI thematic, the Fund’s focus on fundamental real non-U.S. dollar assets offers a potential return stream that is independent of the volatility in the AI cycle. This is supported by the Fund’s current very low correlation to tech dominated equity markets.3
ACTIVITY
There were no new investments during the quarter. Instead, Fund Management directed capital towards four existing holdings — Ingenia Communities Group, Warehouses De Pauw, Savills, and SUNeVision — each of which reinforces one of the Fund’s core investment themes.
Within the Fund’s undersupplied residential theme, Fund Management increased the position in Australian-listed Ingenia Communities Group (“Ingenia”), the country’s largest owner, operator and developer of affordable land-lease lifestyle communities and holiday parks. In August, Ingenia proposed the acquisition of Western Australian residential land developer Peet Limited (“Peet”), which controls more than 26,000 lots across over 40 projects nationally. Fund Management views the transaction favorably as Peet’s land bank provides a long runway to convert an estimated 5,000–7,000 lots into land-lease communities, materially extending Ingenia’s development pipeline at an attractive cost and supporting future returns. The market seemed to underappreciate the transaction, and Ingenia shares sold off following the announcement, creating an opportunity that the Fund used to increase its position at around A$3.60 per share and a substantial discount to our estimate of NAV.
Shortly thereafter, Warburg Pincus made a series of non-binding, all-cash proposals to privatize Ingenia, increasing the offer price from A$4.75 to A$5.05 and, most recently, to A$5.25 per security, conditional on Ingenia abandoning the Peet acquisition. Ingenia’s board has since granted Warburg Pincus non-exclusive due diligence; however, a transaction remains uncertain, as even under a scheme of arrangement, approval of 75% of votes cast by securityholders would be required. In Fund Management’s view, the A$5.25 proposal substantially undervalues Ingenia, particularly on a medium-term view, and the board should not recommend a transaction at these prices. Fund Management believes Ingenia can deliver a mid-teens investment IRR on a standalone basis, underpinned by structural demand drivers unique to Australian land-lease communities, which supports the Fund’s expected return from the position. It is difficult to find real estate companies that combine structural growth drivers with a high-quality management team capable of compounding growth at a rate in the teens for many years. As such, Fund Management would only support a transaction at a meaningfully higher price.
Within the Fund’s industrial/nearshoring/logistics theme, Fund Management increased exposure to Belgian-listed Warehouses De Pauw (“WDP”), a high-quality industrial and logistics owner and developer with a portfolio across Belgium, the Netherlands, and Romania, and a long history of compounding real estate value under the leadership of the controlling de Pauw family. During the quarter, WDP agreed to merge with French logistics REIT Argan, creating an approximately €13 billion pan-European logistics platform with a combined €1 billion development pipeline in execution and 3.2 million square meters of buildable land. The transaction is expected to be completed in the first quarter of 2027 and generate approximately €10 million of annual synergies. In addition, at the end of the quarter, WDP raised equity to fund expansion into Germany and Italy. With these recent deals, WDP is increasingly well-positioned for the structural drivers of European industrial demand, with growing exposure to France and Germany, where rising military spending and a renewed focus on industrial self-sufficiency should support demand, and to Romania, a key beneficiary of nearshoring toward lower-cost Europe.
Within the Fund’s deep value and special situations theme, Fund Management increased its position in London-listed Savills Plc (“Savills”). As discussed in our first-quarter 2026 letter, Savills agreed to acquire the U.S. real estate investment banking group Eastdil Secured. The acquisition closed in August, creating Eastdil Secured Savills, which the company states is now the number two advisor globally for prime commercial real estate transactions above $100 million. Recent conversations with Savills management give us increasing comfort regarding the potential of the combined group, supporting the Fund’s decision to add to the position. Despite the upside, Savills continues to trade at a 4–5 turn EBITDA multiple discount to U.S. peers such as CBRE and JLL. In Fund Management’s view, narrowing this multiple differential could generate 40–50% upside in Savills’ share price—a catalyst that could materialize in the coming periods as Savills shows evidence of the upside of the combined platform, in addition to core regions such as Hong Kong benefiting from improved fundamentals and transaction volumes.
Following on in the deep value and special situations theme, Fund Management also increased exposure to Hong Kong-listed SUNeVision Holdings (“SUNeVision”), the largest datacenter owner and operator in Hong Kong and a subsidiary of Sun Hung Kai Properties. SUNeVision is the Fund’s only datacenter/AI exposure and represents <4% of Fund assets. Fund Management remains cautious on the global data center supply cycle and will only invest in supply-constrained markets in data centers suited to AI inference workloads, which require high connectivity and low latency. SUNeVision fits these criteria. Hong Kong benefits from scarce land, limited new supply, and its role as a regional connectivity hub, with SUNeVision’s carrier-neutral facilities at the center of this network. During the quarter, SUNeVision announced large leasing deals and accelerated its development pipeline, which should drive substantial earnings growth as its capacity, measured in megawatts, more than doubles and support the Fund’s return opportunity. Despite this growth outlook, SUNeVision trades at only 9 times earnings, another example of the valuation disconnect across the Fund’s holdings.
To fund these additions, Fund Management trimmed several holdings that have performed well, while maintaining each as a meaningful position in the Fund. In the Fund’s industrial/nearshoring/logistics exposure, core positions in Mexican owner/developer Corp. Inmobiliaria Vesta (“Vesta”) and Thai/Vietnamese industrial real estate developer Amata Corporation (“Amata”) were both trimmed. Fund Management retains high conviction in Vesta as a long-term holding and beneficiary of nearshoring to Mexico; however, the reweighting simply reflects better relative value elsewhere and helps support the Fund’s overall return opportunity. Similarly, Fund Management retains high conviction in Southeast Asia, benefiting from a ‘China plus one’ transition in supply chains. That said, since initiating a position in Amata about a year ago, shares have more than doubled. Despite the share price rally, Amata shares are modestly valued on earnings and book value ratios relative to their history, so trimming locks in gains while preserving exposure to future returns, in our view.
Within the Fund’s deep value/special situations thematic, Hongkong Land Holdings (“Hongkong Land”) was also reduced. Hongkong Land has generated high returns for the Fund as company management executed a significant turnaround. In addition to ongoing benefits from Hongkong Land’s turnaround and simplification, the company looks set to benefit from a rapidly improving central Hong Kong office market and the prospect of growth in its new real estate investment management platform. Hongkong Land remains a core holding, but at a smaller exposure given relative value found elsewhere and the return already realized.
The Fund’s Glenveagh Properties (“Glenveagh”) position was also trimmed. This high-conviction holding within the undersupplied residential theme has generated excellent returns for the Fund, and the strength of the Dublin, Ireland housing market looks set to continue. Valuation still seems attractive at ~12x forward earnings; however, with total returns of 38% per year over the last three years, the position size was trimmed.
POSITIONING
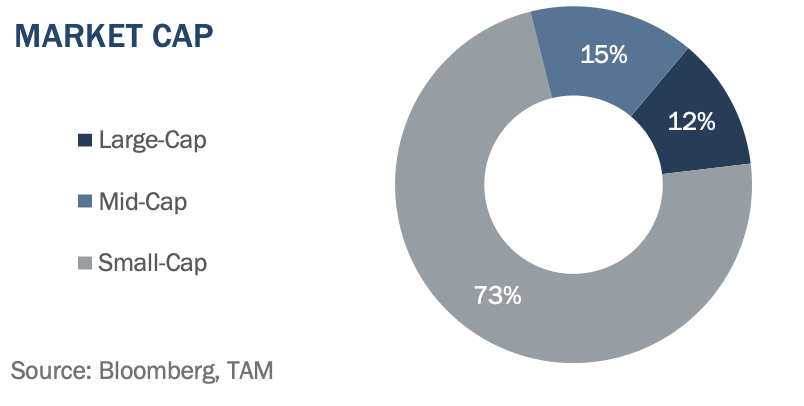
Including the aforementioned activity, the Fund’s allocations remain broadly consistent with recent quarters. The Fund continues to emphasize four key thematics: (i) deep value and special situations, (ii) undersupplied residential markets, (iii) industrial/nearshoring/logistics platforms, and (iv) immature self-storage, alongside a focus on mid-cap companies and diversified geographic exposure, as shown in the following charts. The quarter’s reweighting was largely within themes rather than between them: in residential, the addition to Ingenia was partly funded by the trim of Glenveagh; in industrial, exposure shifted modestly from emerging market nearshoring (Vesta and Amata) toward European logistics (WDP); and within deep value and special situations, capital was recycled from Hongkong Land into Savills and SUNeVision. As a result, the Fund’s emerging market exposure modestly declined during the quarter.



OUTLOOK COMMENTARY – IS HISTORY RHYMING?
During the quarter, Fund Management published a white paper, “Is History Rhyming? Deep value opportunities, falling correlations and non-U.S. dollar real assets for an era of fiscal dominance”. Its central argument is that today’s market setup closely resembles 1999/2000, the start of international real estate’s last major bull market. Then, as now, equity market returns were driven by a narrow group of technology leaders, while international real estate had lagged and traded at deep discounts to private market values. Over the following five years, international real estate delivered total returns of roughly 16% per year, while global equities finished below where they started.
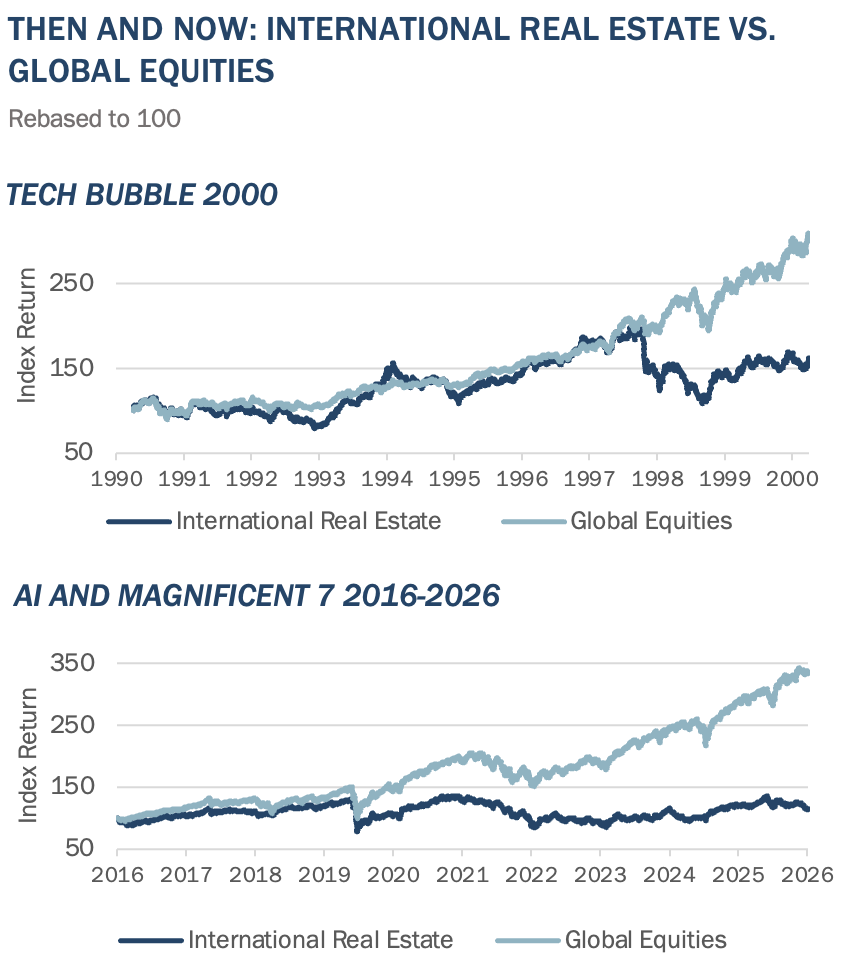
The white paper sets out the following five reasons why Fund Management believes the opportunity is unusual today:
- Narrow markets. Technology and communications now account for over half of the S&P 500, a higher concentration than at the dot-com peak.
- Historic valuation discounts. International real estate trades below 0.8 times book value, and the Fund trades at about 10 times earnings, roughly half the multiple of U.S. REITs, despite high-single-digit earnings growth.
- Falling correlations. The Fund’s correlation with the Nasdaq-100 has fallen from roughly 0.9 to below 0.2, a pattern last seen before 2000.
- Positioned for inflation. Inflation-linked rents, low leverage, and debt that has already repriced help protect the portfolio if price pressures persist.
- Non-U.S. dollar real assets. As U.S. fiscal pressures build, real assets priced outside the dollar, which remains roughly 30% overvalued on a purchasing power parity basis by some estimates, offer valuable diversification.
UNPRECENTED VALUATION DISCOUNT

The full report explores each one of these themes in further detail, including what an era of U.S. fiscal dominance could mean for real assets, how the Fund’s portfolio held up through the 2022 inflation shock, and the growing list of potential catalysts, from privatizations such as Warburg Pincus’s interest in Ingenia this quarter to a broader rotation of capital into real assets. If you would like a copy of the white paper, please contact clientservice@thirdave.com or access the report on our website.
We thank you for your continued support and look forward to writing to you again next quarter. In the interim, please do not hesitate to contact us with any questions, comments, or ideas at realestate@thirdave.com.
Sincerely, The Third Avenue Real Estate Value Team
Quentin Velleley, CFA Portfolio Manager

IMPORTANT INFORMATION
This publication does not constitute an offer or solicitation of any transaction in any securities. Any recommendation contained herein may not be suitable for all investors. Information contained in this publication has been obtained from sources we believe to be reliable, but cannot be guaranteed.
The information in this portfolio manager letter represents the opinions of the portfolio manager(s) and is not intended to be a forecast of future events, a guarantee of future results or investment advice. Views expressed are those of the portfolio manager(s) and may differ from those of other portfolio managers or of the firm as a whole. Also, please note that any discussion of the Fund’s holdings, the Fund’s performance, and the portfolio manager(s) views are as of September 30, 2026 (except as otherwise stated), and are subject to change without notice. Certain information contained in this letter constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue” or “believe,” or the negatives thereof (such as “may not,” “should not,” “are not expected to,” etc.) or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events or results or the actual performance of any fund may differ materially from those reflected or contemplated in any such forward-looking statement. Current performance results may be lower or higher than performance numbers quoted in certain letters to shareholders.
Date of first use of portfolio manager commentary: October 26, 2026
1 The MSCI ACWI ex USA IMI Core Real Estate Index is a free float-adjusted market capitalization index that consists of large, mid and small-cap stocks across 22 Developed Markets (DM) and 24 Emerging Markets (EM) countries engaged in the ownership, development and management of specific core property type real estate. The index excludes companies, such as real estate services and real estate financing companies, that do not own properties. Results for the index are inclusive of dividends and net of foreign withholding taxes.
2 Excess Return refers to the return from an investment above the benchmark. Source: Investopedia
3 On a one-year rolling monthly basis the Fund’s correlation to the U.S. technology-heavy NASDAQ 100 Index (NDX) is 0.06.
Index Source: MSCI. MSCI makes no express or implied warranties or representations and shall have no liability whatsoever with respect to any MSCI data contained herein. The MSCI data may not be further redistributed or used as a basis for other indexes or any securities or financial products. This report is not approved, endorsed, reviewed or produced by MSCI. None of the MSCI data is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. An investor cannot invest directly in an index, and index performance does not reflect the deduction of fees and expenses.
For the Third Avenue Glossary please visit here.

Past performance is no guarantee of future results; returns include reinvestment of all distributions. The above represents past performance and current performance may be lower or higher than performance quoted above. Investment return and principal value fluctuate so that an investor’s shares, when redeemed, may be worth more or less than the original cost. For the most recent month-end performance, please visit the Fund’s website at www.thirdave.com. The gross expense ratio for the Fund’s Institutional and Z share classes is 1.52% and 1.46%, respectively, as of March 1, 2026.
Distributions and yields are subject to change and are not guaranteed.
FUND RISKS: In addition to general market conditions, the value of the Fund will be affected by the strength of the real estate markets. Factors that could affect the value of the Fund’s holdings include the following: overbuilding and increased competition, increases in property taxes and operating expenses, declines in the value of real estate, lack of availability of equity and debt financing to refinance maturing debt, vacancies due to economic conditions and tenant bankruptcies, losses due to costs resulting from environmental contamination and its related clean-up, changes in interest rates, changes in zoning laws, casualty or condemnation losses, variations in rental income, changes in neighborhood values, and functional obsolescence and appeal of properties to tenants. The Adviser’s use of its ESG framework could cause it to perform differently compared to funds that do not have such a policy. The criteria related to this ESG framework may result in the Fund’s forgoing opportunities to buy certain securities when it might otherwise be advantageous to do so, or selling securities for ESG reasons when it might be otherwise disadvantageous for it to do so. For a full disclosure of principal investment risks, please refer to the Fund’s Prospectus.
The fund's investment objectives, risks, charges, and expenses must be considered carefully before investing. The prospectus contains this and other important information about the investment company, and it may be obtained by calling 800-443-1021 or visiting www.thirdave.com. Read it carefully before investing.
Distributor of Third Avenue Funds: Foreside Fund Services, LLC.
Current performance results may be lower or higher than performance numbers quoted in certain letters to shareholders.
Third Avenue offers multiple investment solutions with unique exposures and return profiles. Our core strategies are currently available through '40Act mutual funds and customized accounts. If you would like further information, please contact a Relationship Manager at:


Notice
You are now leaving the Third Avenue Management website and being connected to a third-party website. Please note that Third Avenue Management is not responsible for the information, content or products(s) found on third-party websites.