


Notice
You are now leaving the Third Avenue Management website and being connected to a third-party website. Please note that Third Avenue Management is not responsible for the information, content or products(s) found on third-party websites.
Notice
Third Avenue Management is aware of recent incidents involving unauthorized individuals and groups falsely claiming to represent Third Avenue Management and its affiliates through social media platforms, messaging applications, email, and fraudulent websites. In some cases, these bad actors have used the names, photographs, or identities of Third Avenue employees in an attempt to appear legitimate.
These individuals and websites are not affiliated with, sponsored by, or endorsed by Third Avenue Management.
Third Avenue Management does not solicit investments, provide investment recommendations, or request personal or financial information through social media platforms or messaging applications such as WhatsApp, Telegram, Signal, or similar services.If you receive a suspicious communication claiming to be from Third Avenue Management, we encourage you to verify its authenticity before responding or providing any personal or financial information. If you are unsure whether you are communicating with an authorized representative of Third Avenue, please contact us directly using the contact information available on our official website.
Third Avenue Management, its affiliates, directors, officers, employees, and agents are not responsible for communications, representations, or activities conducted by unauthorized third parties. If you believe you have been the target of an impersonation or investment scam, or that you or someone you know has been a victim of fraud, please contact your local law enforcement agency and report the incident to the appropriate authorities. In the United States, suspected internet fraud can also be reported to the Federal Bureau of Investigation's Internet Crime Complaint Center (IC3) at https://www.ic3.gov/.
Notice
You are now leaving the Third Avenue Management website and being connected to a third-party website. Please note that Third Avenue Management is not responsible for the information, content or products(s) found on third-party websites.
September 30, 2026
Real Estate Value Fund
Real Estate Value Fund Q326


Dear Fellow Shareholders,
We are pleased to provide you with the Third Avenue Real Estate Value Fund’s (the “Fund”) report for the quarter ended September 30, 2026. For the most recent period, the Fund generated a return of -8.59% (after fees). In comparison, the Fund’s most-relevant benchmark, the MSCI ACWI IMI Core Real Estate Index¹, generated a return of -5.33% (before fees) over the same time-period.
The primary contributors to performance during the period included the Fund’s investments engaged in “resource conversion” (Segro plc and Ingenia Communities) and several other international property companies (Savills plc, CK Asset Holdings, and Wharf Holdings). Notwithstanding, these gains were more than offset by detractors during the quarter, including the Fund’s investments in the preferred equity of Fannie Mae and Freddie Mac, as well as other U.S.-based residential businesses (Brookdale Senior Living, PulteGroup, and Five Point Holdings). Further insights into these enterprises, as well as the Fund’s most recent additions (Scentre Group and Home Depot) are included herein.
Recognizing that returns will vary from quarter-to-quarter, Fund Management continues to believe the Fund’s long-term results are the most relevant scorecard. To that end, the Third Avenue Real Estate Value Fund has generated an annualized return of +8.18% since its inception in 1998 (after fees). This performance also indicates that an initial investment of $100,000 in the Fund would have a market value exceeding $900,000 at quarter-end (with distributions reinvested)—or more than what the same $100,000 would have totaled in a passive mutual fund tracking the benchmark over the same period.

ACTIVITY
During the quarter, Third Avenue’s real estate team participated in several industry events, with one clear message resonating throughout: a widening divergence of fundamental performance across listed real estate. For instance, nearly 100 property companies presented at the BofA Securities Global Real Estate Conference in New York, noting strengthening supply-and-demand trends for most types of retail real estate, with multifamily supply remaining elevated in several U.S. regions. In addition, valuations seemed much more favorable for international property companies, particularly in comparison to some of the larger U.S. companies involved with senior housing and data centers.
Meanwhile, the 500-plus attendees at the Zelman Housing Summit in Boston were presented an even more nuanced view of the U.S. residential markets, with strong pockets of demand identified in niche sectors such as manufactured housing and active-adult. Notwithstanding, various factors such as the “lock-in- effect” were generally limiting transaction activity in the existing home market, with affordability concerns leading to more subdued activity in new home construction, pointing to significant consolidation opportunities across the value chain.
Along these lines, the Fund initiated positions in the common stock of Scentre Group and Home Depot during the quarter.
Scentre Group is an Australian-based real estate investment trust (“REIT”) that is the leading owner and operator of retail-led destinations in Australia and New Zealand. Established in 2014 after being split out of Westfield Corp. (a former Fund holding that was acquired by Unibail-Rodamco), the company’s portfolio is today comprised of 42 destinations that are primarily located in key urban corridors within Sydney, Melbourne, Brisbane, and Perth—markets that are viewed to be supply constrained with less than half the retail square footage of U.S. markets on a per capita basis. Additionally, the Westfield-branded centers tend to have grocery-anchors sitting alongside more traditional retailers, driving a steady mix of traffic. As a result, Scentre Group’s portfolio is essentially fully leased with a 99.8% occupancy rate and considered to be one of the most productive retail portfolios globally with more than 550 million customer visits annually and retail sales exceeding $1,700 AUD per square foot (“sf”) on average.
At the same time, the company is well-financed with a net-debt-to-asset ratio of approximately 35%. Therefore, the company has ample resources to pursue “value enhancing” initiatives, including repurposing less productive department store space to accommodate more appealing lifestyle concepts such as its $240 million AUD renovation currently underway at Westfield Bondi. Importantly, Scentre Group is also in the early stages of further densifying its urban land positions, primarily by adding residential components with entitlements already in place for more than 20,000 residential units, with the potential to add 80,000 units in total over time.
Despite these attributes, Scentre Group has been trading at a meaningful discount to its reported Net-Asset Value (“NAV”) amid broader volatility in the “A-REIT” space more recently. As a result, the Fund was able to establish a position in Scentre Group common at prices that imply a 7.0% cap rate (or initial yield) for its premier portfolio, with only a modest uplift for its third-party management business and development assets. In Fund Management’s opinion, this represents an attractive basis for such scarce assets—especially if Scentre Group’s cash flows increase along with its favorable lease terms (e.g., CPI plus 2.0%) and its management team executes on its plan of selling joint venture stakes in line with appraised values while reinvesting the proceeds into its pipeline on an accretive basis.
Founded in 1978, Home Depot is the largest home improvement retailer in North America, with a network of more than 2,300 stores across the U.S., Canada, and Mexico. The company is well-recognized for its leading position in this distinct retail segment, which is effectively a duopoly alongside industry peer Lowe’s (a former holding in the Fund) with more rational dynamics than other retail channels. In addition, demand for its key segments tends to be resilient with nearly 50% of purchases tied to the professional buyer focused on the repair and remodel market (“R&R”), whereas the remaining do-it-yourself (“DIY”) business seems less threatened by e-commerce given the bulky and same-day nature of its products.
In our view, what is not as well recognized, though, is Home Depot’s substantial asset base that includes an ownership interest in more than 200 million square feet of real estate, as well as modest levels of “maintenance capex”, leaving substantial free cash flow that can be utilized for value-enhancing initiatives. Consequently, Home Depot has been able to generate approximately $15 billion of free cash flow per year over the past four years, on average, despite (i) existing home sales—which drive R&R spending—remaining around decade-low levels over the time period and (ii) a lack of storm activity in North America more recently, which can account for $5-6 billion in related spending.
Instead of strictly returning this capital to shareholders as in previous years, Home Depot’s disciplined management team is utilizing this cash flow, along with its strong balance sheet, to expand into the distribution space with the aim of providing large-scale professional buyers with a single-point source for building products and materials. In conjunction with this effort, Home Depot has combined its existing distribution business (HD Supply) with more recent acquisitions (SRS Distribution and GMS, among others) to form one of the leading multi-product distribution platforms in the U.S. with more than $16 billion of “run rate” revenues.
As Fund Management has pointed out before though, the distribution business can be challenging with low margins, capital intensity, and inventory obsolescence risk. That said, scaled players can operate more efficiently, those that remain well-capitalized can take market share through cycles, and diversified participants can cross-sell products and services to enhance margins over time. With Home Depot qualifying on all three fronts, it is Fund Management’s expectation that the company will continue to take market share within its distribution segment (where it accounts for less than 10% of estimated market share) while its more established home improvement segment (with an approximate 30% share of home improvement retail spending) returns to more normalized levels of profitability over time. Such a combination would not only result in a significant “step up” in Home Depot’s cash flows from current levels but also lead to an NAV that is well ahead of what is implied in its common stock, in our view.
The Fund also exited its position in the common stock of Segro (the leading owner and operator of industrial and logistics properties in the U.K. and Western Europe) after it agreed to be acquired by Prologis (a U.S.-REIT that is the largest owner of industrial and logistics properties globally) during the quarter. The transaction was cemented after Prologis raised its offer price to a level that provided a compelling “change of control premium”, as well as a cash component for U.K. holders restricted from owning shares in Prologis as a U.S.-listed REIT. Prior to the disposition, the Fund had held Segro common for more than 15 years, a period of which Segro’s management team transformed the company and provided shareholders with a +12.0% annualized return. Nonetheless, the Fund is positioned to participate in the performance of Segro’s strategic locations and development opportunities going forward through its remaining position in Prologis. While final projections are still being formulated, it is our view that the combined portfolios will offer significant efficiencies, as well as represent an even more strategic European platform as the largest industrial owner, developer, and manager in the region.
Outside of these changes, the Fund’s activity was relatively modest in nature. Of note, the Fund increased its investments in the common stock of Brookdale Senior Living, Champion Homes, Ingenia Communities and Savills plc with the price-to-value proposition becoming more compelling in each instance. The Fund also trimmed back WESCO and Freddie Mac preferred, exited D.R. Horton, and extended its British Pound and Hong Kong Dollar hedges for portfolio management purposes.
POSITIONING
Following these changes, the Fund had 37.8% of its capital invested in U.S.-based companies focused on Residential Real Estate, including those involved with: Homebuilding (Lennar Corp., PulteGroup, and Champion Homes); Niche Rental Platforms (Sun Communities, AMH, and Brookdale Senior Living); Building Products (Five Point, Home Depot, and Weyerhaeuser); and Mortgage and Title Insurance (Fannie Mae, Freddie Mac, and Fidelity National). In Fund Management’s view, each issuer has a well-established position in the residential value chain and is underpinned by supportive fundamental drivers long-term, including: (i) notable demographic shifts, (ii) favorable supply-and-demand conditions, and (iii) industry dynamics favoring scaled players.
An additional 29.5% of the Fund’s capital was invested in North American-based companies involved with Commercial Real Estate, including: Real Estate Services (CBRE Group, JLL, and FirstService); Asset Management (Brookfield Corp.); Industrial and Logistics (Prologis, First Industrial, and WESCO); and Self-Storage (U-Haul Holdings). In Fund Management’s opinion, these holdings represent platforms that would be very difficult to reassemble. They also comprise select pockets of commercial real estate that seem supported long-term with (i) diverse demand drivers, (ii) limited maintenance capex and obsolescence risk, and (iii) prospects for value-enhancing investments.
The Fund also had 28.3% of its capital invested in International Real Estate companies. These holdings are largely focused on the same activities as outlined above, but with leading platforms in their respective regions. At quarter-end, these included companies involved with: Commercial Real Estate (Big Yellow, CK Asset, Jardine Matheson, Scentre Group, Hang Lung Group, and Wharf Holdings); Residential Real Estate (Berkeley Group and Ingenia Communities); and Real Estate Services (Savills and Accor). The holdings are also listed in developed markets where Fund Management believes there are (i) adequate disclosures and securities laws and (ii) ample opportunities for resource conversion or change-of-control transactions (i.e., the U.K., Australia, France, Hong Kong, and Singapore).
The remaining 4.4% of the Fund’s capital is in Cash, Debt & Options. These holdings include U.S.-Dollar based cash and equivalents, short-term U.S. Treasuries, and hedges relating to certain foreign currency exposures (Hong Kong Dollar and British Pound).

FUND COMMENTARY
In The Price of Time: The Real Story of Interest, author Edward Chancellor examines centuries of financial history, with a particular focus on historical interest rates and periods of financial exuberance. Within the intelligent work, he also observes that “few things in finance are harder to predict than the direction of interest rates” with certain periods of low rates (and high debt) begetting even lower rates, while excessive fiscal deficits have led to significantly higher bond yields at times. Chancellor also points out several instances of fiscal dominance (i.e., when a government’s debt burden dictates monetary policy), with bond yields being suppressed, leading to negative real rates.
On the other hand, Chancellor suggests that periods of financial exuberance are more likely to be identified in the moment, particularly when profits “detach from real economic activities” and the financial sector crowds out the “real economy”. In fact, he notes the Bank for International Settlements (“BIS”) as a prime example, with their team anticipating the “financial crisis” that ensued around 2008.
Interestingly, BIS published its 2026 Annual Economic Report more recently, with the team outlining several considerations for global economies, including a number related to Artificial Intelligence (“AI”). For instance, BIS notes that the “intense competition” of AI-related investments raises the risk of firms “overcommitting resources” for investment purposes. As a result, any “reversal of AI optimism” would have significant consequences with “AI firms rising leverage and growing footprint in the capital markets”.
No doubt a sobering take, it does not seem to be a widely held view within listed real estate as the data center and AI infrastructure-related companies have been among the leading performers so far this year. In fact, the J.P. Morgan U.S. Digital Infrastructure Index had increased by +24.2% through the first three quarters of the 2026 calendar year—despite yields for 10-year U.S. Treasury Notes experiencing the largest quarterly move upward in more than thirty years in the recent quarter.
Meanwhile most other real estate sectors have posted negative performance alongside this rapid shift given their perceived interest rate sensitivity, including several of the Fund’s holdings. Of note, the Fund’s investments in real estate service companies, homebuilders, and other transaction-oriented property companies weighed on performance in the quarter. The Fund’s investments in the preferred equity of Fannie Mae and Freddie Mac also detracted from returns with the timeline for these entities attaining targeted capital ratios seemingly being extended (although still aligning with the Congressional Budget Office’s Analysis on Recapitalizing Fannie Mae and Freddie Mac Through Administrative Action).
In Fund Management’s experience, these differentiated holdings can detract from performance over shorter periods of time, particularly due to their perceived “economic sensitivity” and lower levels of “current yield” relative to more widely held REITs. That said, it remains our view that such businesses are indeed much better suited to navigate this period of higher “real rates” over the long-term. It is for that reason that Fund Management anticipates the Third Avenue Real Estate Value Fund’s capital remaining concentrated in issuers with the following attributes:
1) Super-strong financial positions, with the estimated loan-to-value ratio for the Fund’s holdings below 15% on average, or less than half of relevant benchmarks. At the same time, approximately three-quarters of the Fund’s capital is invested in “C-corps”, which can retain capital, as opposed to REITs that are largely required to distribute income. As a result, the Fund’s holdings seem to face less “refinancing risk” than the broader real estate space, while being less reliant on the capital markets to fund operations and other initiatives.
2) Securities trading at discounts to durable values, with the underlying holdings trading at nearly a 30% discount to Fund Management’s conservative estimates of NAV, when viewed in the aggregate. In fact, several issuers in the Fund are trading at multi-decade lows on certain fundamental measures. These prices are also well below what a “control buyer” would pay for these strategic platforms, particularly when factoring in their essential nature and lack of technological obsolescence risk, in our view.
3) Prospects to increase cash flows and NAV, with the Fund’s select-set of real estate holdings generally exhibiting one of four drivers to create (or surface) incremental value over time. Such factors include pricing power (i.e., higher rents), market share opportunities (e.g., additional volumes), operating leverage (e.g., lease-up potential), or prospects for value-enhancing resource conversion activities.
When viewed alongside a lack of direct investments in data centers and related infrastructure, the Fund seems distinctly positioned as a value alternative within listed real estate—and one that is compelling from a prospective return basis, in our view, with the price-to-value gap for the Fund’s holdings at more than two times the long-term average amid recent volatility. Chancellor might agree. As he also noted in The Price of Time, equity returns are “inversely correlated with valuations” over the long-term.
We thank you for your continued support and look forward to writing to you again next quarter. In the meantime, please don’t hesitate to contact us with any questions or comments at realestate@thirdave.com.
Sincerely,
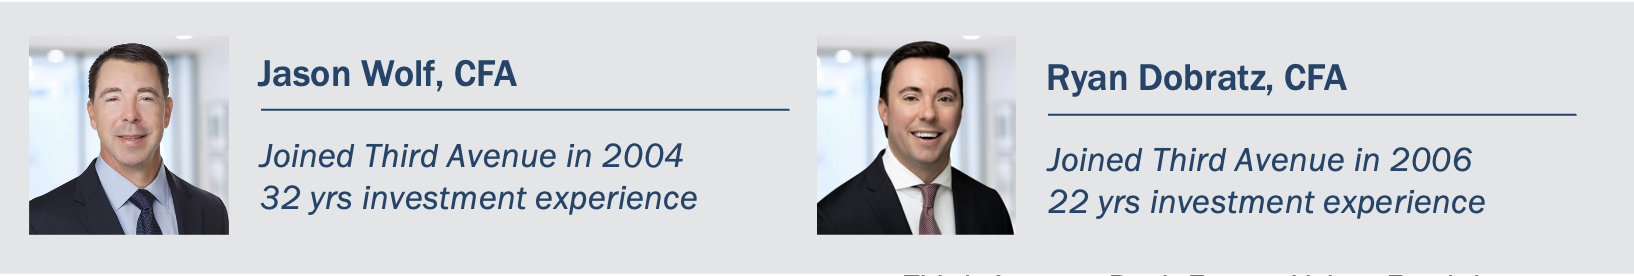
The Third Avenue Real Estate Value Team
IMPORTANT INFORMATION
This publication does not constitute an offer or solicitation of any transaction in any securities. Any recommendation contained herein may not be suitable for all investors. Information contained in this publication has been obtained from sources we believe to be reliable, but cannot be guaranteed.
The information in this portfolio manager letter represents the opinions of the portfolio manager(s) and is not intended to be a forecast of future events, a guarantee of future results or investment advice. Views expressed are those of the portfolio manager(s) and may differ from those of other portfolio managers or of the firm as a whole. Also, please note that any discussion of the Fund’s holdings, the Fund’s performance, and the portfolio manager(s) views are as of September 30, 2026 (except as otherwise stated), and are subject to change without notice. Certain information contained in this letter constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue” or “believe,” or the negatives thereof (such as “may not,” “should not,” “are not expected to,” etc.) or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events or results or the actual performance of any fund may differ materially from those reflected or contemplated in any such forward-looking statement. Current performance results may be lower or higher than performance numbers quoted in certain letters to shareholders.
Date of first use of portfolio manager commentary: October 22, 2026
1The MSCI ACWI IMI Core Real Estate Index is a free float-adjusted market capitalization index that consists of large, mid and small-cap stocks across 23 Developed Markets (DM) and 24 Emerging Markets (EM) countries engaged in the ownership, development, and management of specific core property type real estate. The index excludes companies, such as real estate services and real estate financing companies, that do not own properties. Results for the index are inclusive of dividends and net of foreign withholding taxes.
For the Third Avenue Glossary please visit here.

Past performance is no guarantee of future results; returns include reinvestment of all distributions. The above represents past performance and current performance may be lower or higher than performance quoted above. Investment return and principal value fluctuate so that an investor’s shares, when redeemed, may be worth more or less than the original cost. For the most recent month-end performance, please visit the Fund’s website at www.thirdave.com. The gross expense ratio for the Fund’s Institutional, Investor and Z share classes is 1.18%, 1.43% and 1.11%, respectively, as of March 1, 2026.
Distributions and yields are subject to change and are not guaranteed.
Risks that could negatively impact returns include: overbuilding and increased competition, increases in property taxes and operating expenses, lack of financing, vacancies, environmental contamination and its related clean-up, changes in interest rates, casualty or condemnation losses, and variations in rental income.
The fund's investment objectives, risks, charges, and expenses must be considered carefully before investing. The prospectus contains this and other important information about the investment company, and it may be obtained by calling 800-443-1021 or visiting www.thirdave.com. Read it carefully before investing.
Distributor of Third Avenue Funds: Foreside Fund Services, LLC.
Current performance results may be lower or higher than performance numbers quoted in certain letters to shareholders.
Third Avenue offers multiple investment solutions with unique exposures and return profiles. Our core strategies are currently available through '40Act mutual funds and customized accounts. If you would like further information, please contact a Relationship Manager at:


Notice
You are now leaving the Third Avenue Management website and being connected to a third-party website. Please note that Third Avenue Management is not responsible for the information, content or products(s) found on third-party websites.